Federal Reserve Chairman Kevin Warsh told attendees at the Jackson Hole Economic Symposium on Friday that the U.S. economy has reached a “hinge point in history,” arguing that the assumptions which shaped economic policy for the past two decades no longer describe the world in front of us. He repeated a condensed version of the argument two days later at the opening session of the G20.
https://twitter.com/FoxNews/status/1900000000000000000
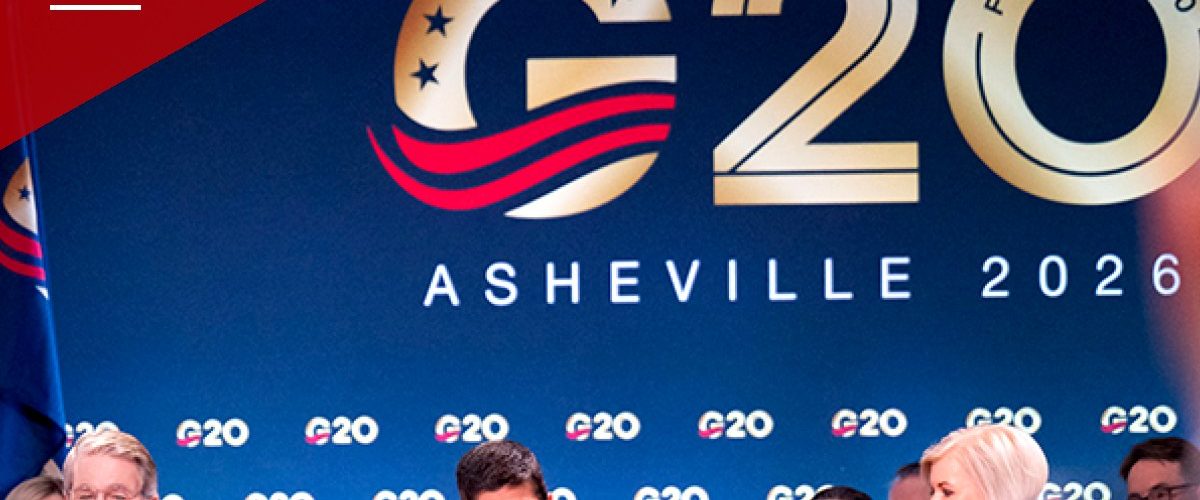
Warsh’s remarks came in Jackson Hole, Wyoming, on August 28, 2026. He followed up Monday, August 31, at the G20 Finance Ministers and Central Bank Governors’ meeting in Asheville, North Carolina, where he appeared alongside Treasury Secretary Scott Bessent.
Warsh credited the phrase “hinge point” to George Shultz, the former Reagan-era Treasury and State Secretary who mentored Warsh and co-authored the 2020 book A Hinge of History with James Timbie. Shultz argued the world had reached an inflection point on par with the years after World War II, driven by fast-moving technology and shifting demographics that had outpaced institutions built for an earlier era. “The near future is not going to be like the near past,” Shultz said of the book’s thesis.
From Scarce Demand to Scarce Labor
For most of the past twenty years, U.S. and global economic policy operated on the assumption that demand, not supply, was the binding constraint — the era of “secular stagnation” and a global glut of savings chasing too few worthwhile investments. That assumption justified near-zero interest rates, central-bank bond buying, and government deficit spending meant to put idle labor and capital to work.
Warsh argues that picture is now reversed. He pointed to a surge of private investment in artificial intelligence, data centers, and energy infrastructure, with business capital spending growing at roughly nine percent — the fastest pace since 2021, and notably not the product of a rebound from a shutdown-driven collapse. He suggested the Fed’s long-standing estimate that the economy’s real growth potential sits around two percent may be built on outdated assumptions, since AI could function as something close to a new factor of production and lift productivity growth well beyond that ceiling.
At the same time, labor-force growth has slowed sharply. Warsh’s framing implies that counting jobs created is a much weaker measure of policy success when the workforce itself is barely expanding. A policy that adds a million jobs to produce the same output as one that adds a hundred thousand jobs through better machines and software is, in his view, the inferior policy — not the superior one.
Policy Implications
The digest built around Warsh’s remarks lays out several consequences that follow from treating labor as the scarce resource rather than demand:
- Immigration policy tight enough, and visa fees high enough, that employers cannot simply substitute cheap imported labor for investment in machinery and productivity.
- An end to treating maximum college enrollment as an economic goal in itself, with more emphasis on apprenticeships and vocational training, a wind-down of the federal student loan program, and retirement of student visas and post-graduation work programs as a backdoor way of expanding the college-educated labor supply.
- Permitting, tax, and regulatory policy judged by whether it expands domestic capacity in energy, critical minerals, transportation, and power infrastructure.
- Shrinking government payrolls — something the digest notes the Trump administration has already been doing — to free labor for more productive private-sector work, on the theory that government borrowing now competes with private investment for scarce capital rather than absorbing idle resources.
The argument extends to how success itself should be measured. Warsh has said policymakers can observe economic activity but cannot directly observe aggregate supply — it has to be inferred — partly because today’s statistical tools were built during the Great Depression to watch for demand shortfalls, not supply constraints. The digest calls for a shift away from headline GDP and payroll counts toward measures like GDP per capita, output per worker, productivity, real wages, and capital formation.
Proponents of this view argue the payoff could be substantial: higher productivity could ease pressure on Social Security by letting fewer workers support more retirees without steep tax hikes, while tighter labor markets could raise wages, narrow income inequality, and encourage earlier family formation.
Shultz’s original formulation treated a
Add comment